

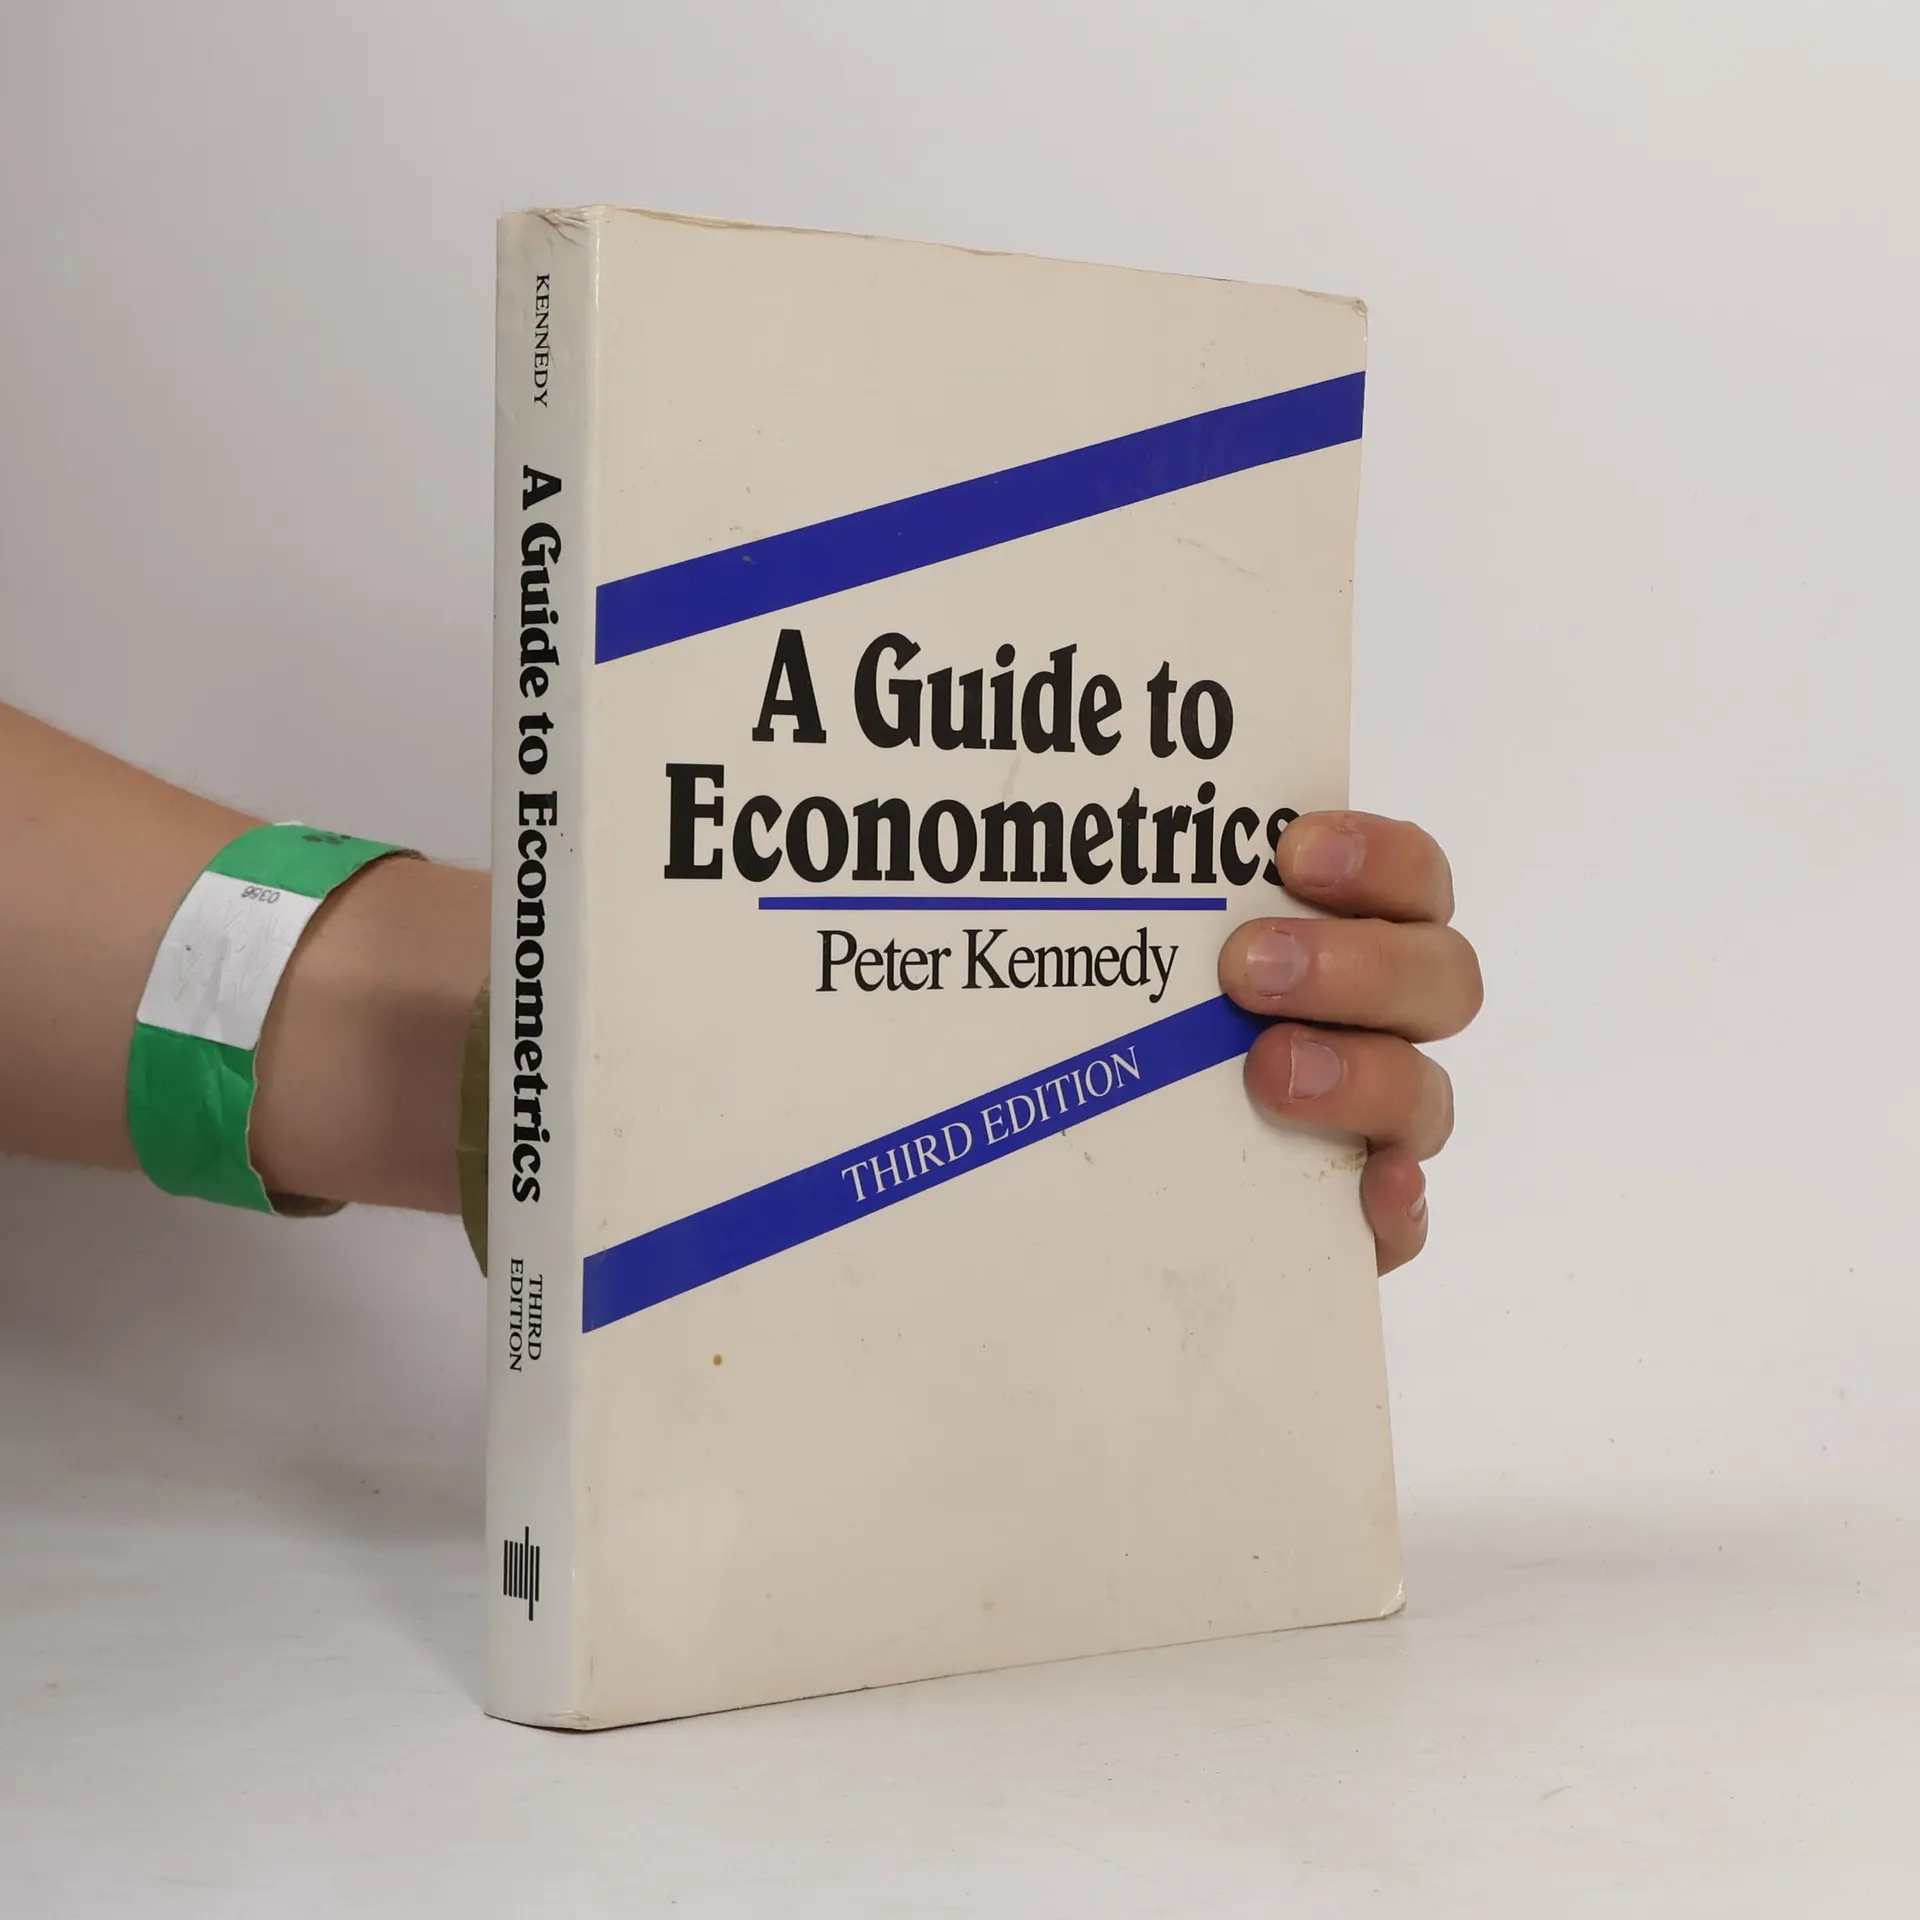
Viac o knihe
A Guide to Econometrics has established itself as a preferred text for teachers and students throughout the world. It provides an overview of the subject and an intuitive feel for its concepts and techniques without the notation and technical detail that characterize most econometrics textbooks. The fifth edition has two major additions, a chapter on panel data and an innovative chapter on applied econometrics. Existing chapters have been revised and updated extensively, particularly the specification chapter (to coordinate with the applied econometrics chapter), the qualitative dependent variables chapter (to better explain the difference between multinomial and conditional logit), the limited dependent variables chapter (to provide a better interpretation of Tobit estimation), and the time series chapter (to incorporate the vector autoregression discussion from the simultaneous equations chapter and to explain more fully estimation of vector error correction models). Several new exercises have been added, some of which form new sections on bootstrapping and on applied econometrics. This edition is for sale in all of the Americas, the West Indies, and U.S. dependencies only.




Nákup knihy
A Guide to Econometrics, Peter Kennedy
- Jazyk

- Rok vydania
- 1992
- Väzba
- (mäkká),
- Stav knihy
- Dobrá
- Cena
- 1,99 €
Tu nám chýba tvoja recenzia
- Titul
- A Guide to Econometrics
- Jazyk
- anglicky
- Autori
- Peter Kennedy
- Vydavateľ
- MIT Press
- Rok vydania
- 1992
- Väzba
- mäkká
- Počet strán
- 410
- ISBN10
- 0262610809
- ISBN13
- 9780262610803
- Série
- Štítky
- Byznys, Učebnice matematiky, Financie
- Hodnotenie
- 4,25 z 5
- Anotácia
- A Guide to Econometrics has established itself as a preferred text for teachers and students throughout the world. It provides an overview of the subject and an intuitive feel for its concepts and techniques without the notation and technical detail that characterize most econometrics textbooks. The fifth edition has two major additions, a chapter on panel data and an innovative chapter on applied econometrics. Existing chapters have been revised and updated extensively, particularly the specification chapter (to coordinate with the applied econometrics chapter), the qualitative dependent variables chapter (to better explain the difference between multinomial and conditional logit), the limited dependent variables chapter (to provide a better interpretation of Tobit estimation), and the time series chapter (to incorporate the vector autoregression discussion from the simultaneous equations chapter and to explain more fully estimation of vector error correction models). Several new exercises have been added, some of which form new sections on bootstrapping and on applied econometrics. This edition is for sale in all of the Americas, the West Indies, and U.S. dependencies only.